PIDM RM250,000 Deposit Insurance: Multiple Accounts, Joint Accounts & Digital Banks Explained
Malaysia's PIDM covers eligible deposits up to RM250,000 per depositor per member bank—not per savings account. Learn joint-account limits, Islamic vs conventional deposits, digital banks, e-wallets and which investments are excluded.

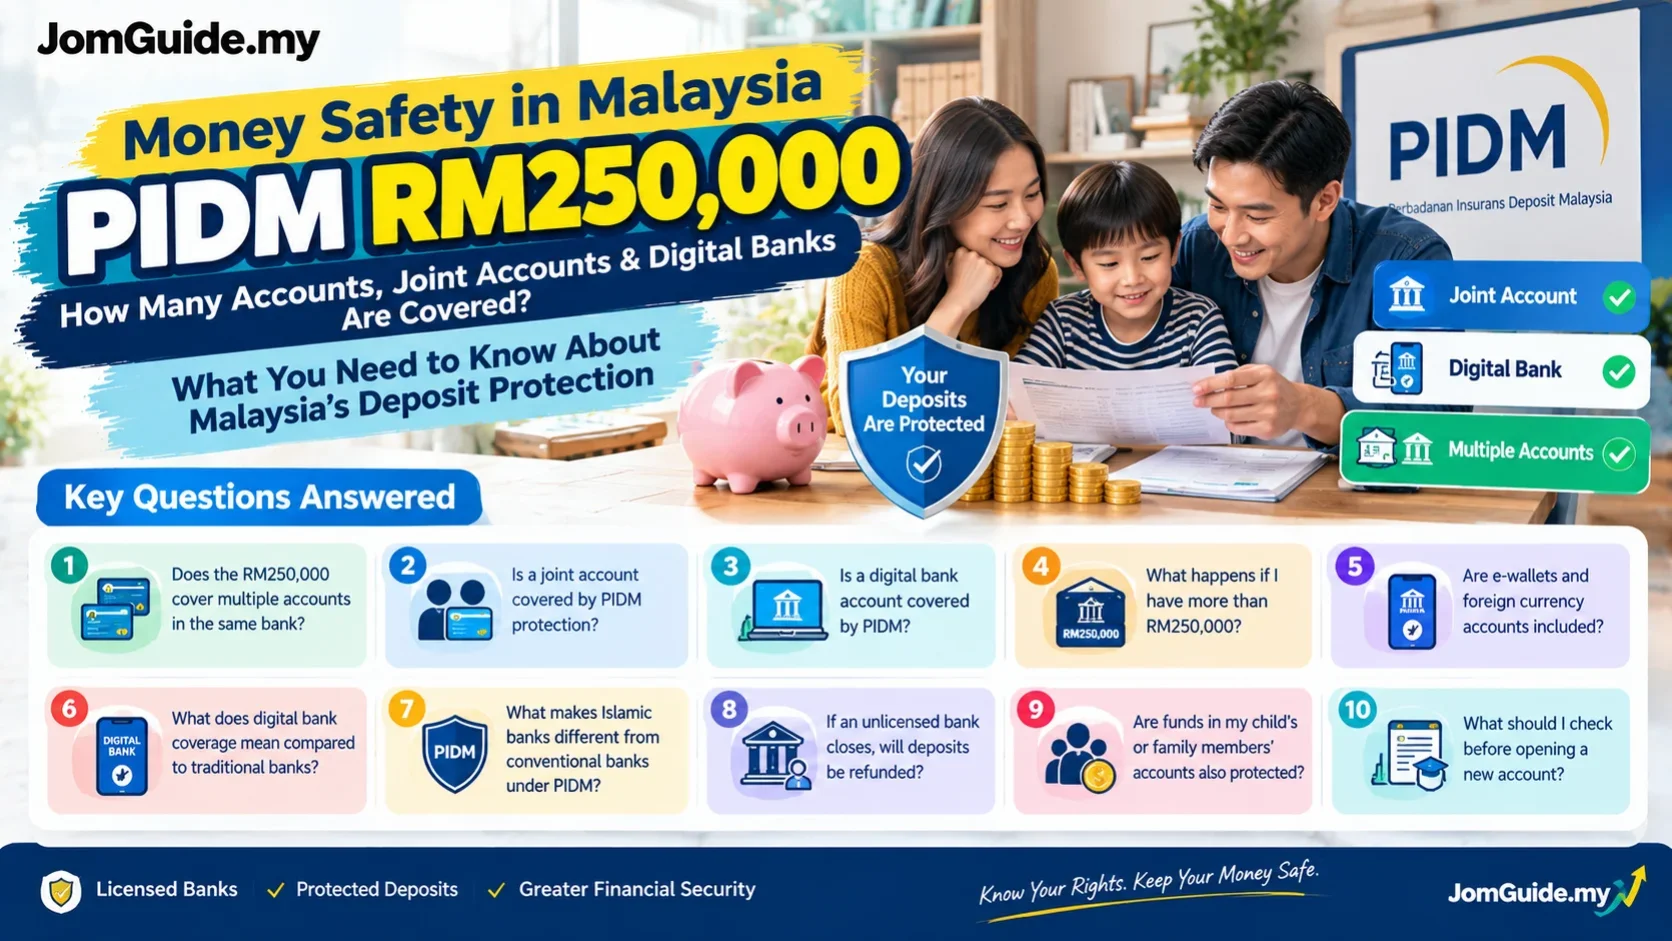
Source: PIDM Official Deposit Insurance System, Deposit Insurance FAQs, e-money/digital bank FAQs (checked 29 Oct 2026)
Verified on 29 October 2026. A bank saying “PIDM protected up to RM250,000” does not mean you get another RM250,000 of cover each time you open a savings account or fixed deposit. Malaysia's deposit-insurance rule is generally RM250,000 per depositor, per PIDM member bank for eligible deposits. Multiple deposits in the same protection category at the same member bank are aggregated, and the limit includes principal plus interest or returns. PIDM Deposit Insurance System; official FAQs.
PIDM protects eligible bank deposits in the unlikely event of a member bank failure. It is not an investment-return guarantee, an anti-scam reimbursement promise or cover for every product promoted by a banking group.
Which financial products are PIDM-insured?
| Product | Deposit-insurance treatment |
|---|---|
| Savings and current accounts at a member bank | Generally eligible, if specifically listed as insured deposits |
| Eligible fixed deposits | Covered under the applicable protection category |
| Eligible Islamic deposit accounts | Covered, with distinct Islamic deposit-insurance limits |
| Eligible foreign currency deposits | Covered, converted and aggregated as required |
| Unit trusts, equities, investment funds | Not covered by deposit insurance |
| Gold/silver investment accounts and cryptocurrencies | Not covered |
| Investment accounts or other non-qualifying products | Not automatically covered |
| Non-bank e-wallet balances | Not directly insured as an individual's bank deposit |
A product can be sold by a PIDM member bank and still be uninsured if it is an investment rather than a qualifying deposit. Check the bank's actual product-disclosure document and deposit-insurance information, not just its logo. PIDM's protected/excluded product list.
One bank, three accounts: the RM250,000 calculation
Consider a hypothetical Malaysian depositor with three eligible conventional deposit accounts at the same member Bank A:
| Account | Hypothetical balance |
|---|---|
| Savings | RM100,000 |
| Current | RM100,000 |
| Fixed deposit | RM80,000 |
| Total | RM280,000 |
For that depositor in that category, RM250,000 is the maximum insured amount, not RM750,000. The additional RM30,000 is not guaranteed by PIDM deposit insurance. If the bank failed, recovery of uninsured amounts would depend on the applicable resolution or liquidation process.
This is a coverage illustration, not advice to open or fund any particular account. PIDM publishes similar examples on its official DIS guide.
Does a different branch count as a new bank?
No. Different branches of the same legal member bank count together for the applicable limit. Eligible deposits at different PIDM member banks, however, receive separate limits. Verify the actual member-bank entity using PIDM's list, rather than assuming two brand names necessarily represent different banking licences.
What about Islamic versus conventional deposits?
PIDM provides separate RM250,000 limits for eligible conventional deposits and eligible Islamic deposits. This is a distinction between protected deposit categories, not an invitation to treat every Islamic-labelled investment as an insured deposit. Eligible foreign currency deposits do not automatically form a separate RM250,000 category merely because they are denominated in another currency. PIDM FAQs.
Joint accounts: is RM250,000 available to each joint owner?
No. PIDM's illustration makes the distinction clear: a single joint-ownership combination has a collective RM250,000 maximum, not RM250,000 for each named joint holder.
Suppose A and B hold two eligible joint accounts with the same member bank and the same owners, each with RM50,000. Their combined qualifying balance for that joint combination is RM100,000, not two separate RM250,000 allowances. This joint protection is calculated separately from the applicable individual-account protection, subject to PIDM's records and rules.
Different joint-owner combinations—such as A+B versus A+B+C—may be eligible for separate joint-account categories, provided ownership particulars are fully recorded. PIDM requires details such as the joint holders' names, addresses and identification information in the member bank's records. Merely renaming a product doesn't create protection. PIDM joint-account guidance.
Digital bank versus e-wallet: not the same
A licensed digital bank that is a PIDM member has eligible deposits protected under the same general insurance framework as other member banks. The fact that the banking relationship operates through an app does not remove the protection.
A non-bank e-money issuer, by contrast, is not a licensed deposit-taking bank. E-money itself is not directly PIDM-insured. Applicable rules may require customer funds to be held in a trust account at a bank; where that bank is a PIDM member and the trust deposit meets the relevant conditions, there may be protection for the underlying trust money. This is not the same as saying every e-wallet balance has a personal RM250,000 PIDM guarantee. PIDM's digital bank and e-money FAQ.
How to check your own deposit protection
Step 1 — Bank: Check whether the actual legal banking entity is on PIDM's member-bank list.
Step 2 — Product: Read the product disclosure sheet or the bank's insured-deposit information. Check that the specific account is a qualifying deposit, rather than an investment product.
Step 3 — Ownership: Distinguish individual, joint, company or other legal ownership categories. Don't assume one blanket method for all.
Step 4 — Aggregate: Count other eligible accounts in the same member bank and insurance category. Principal and interest/returns can contribute to the RM250,000 ceiling.
Step 5 — Records: Keep the bank's ownership and contact information accurate. Eligible deposits are automatically and freely insured; there is no routine upfront “PIDM protection application fee”.
Frequently asked questions
RM250,000 per account or per bank? Generally per depositor per member bank, with aggregation of accounts in the same qualifying category.
Can two joint owners each claim RM250,000 for one joint account? No. The relevant joint-owner combination has a combined limit of RM250,000, subject to PIDM's rules.
Is a fixed deposit's interest included? Yes, principal and interest/returns form part of the protected amount.
Are unit trusts sold at banks protected? No, they are investment products rather than PIDM-insured deposits.
Do I need to register for PIDM protection? No. Qualifying deposits are covered automatically, without premiums paid by depositors.
Sources: PIDM Deposit Insurance System, Deposit Insurance FAQ, PIDM: digital banks versus e-money. Checked 29 October 2026. General educational content, not an individual product recommendation.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.
Related articles
More in Jom Money-
Driving Into Singapore From 2027: VEP Rises to S$50 a Day, Free Days and Evening Hours Scrapped. Here's What It Costs You
-
STR 2026 Phase 4 Is Being Paid: Up to RM500 for Households, RM150 for Seniors, 4–6 November, New Recipients From the 16th
-
When Is STR 2026 Phase 4 Paid? Not Announced Yet: What You Can Do Now, Plus STR 2027 Applications