Home Flooded? Whether Your Insurance Pays, Houseowner vs Householder, and What Condo Owners Must Cover Themselves
The fire policy your bank asked for may not cover floods, and a condo's master policy won't pay for your furniture. How Houseowner and Householder cover work, flood extensions, the average clause and how to claim after a flood.

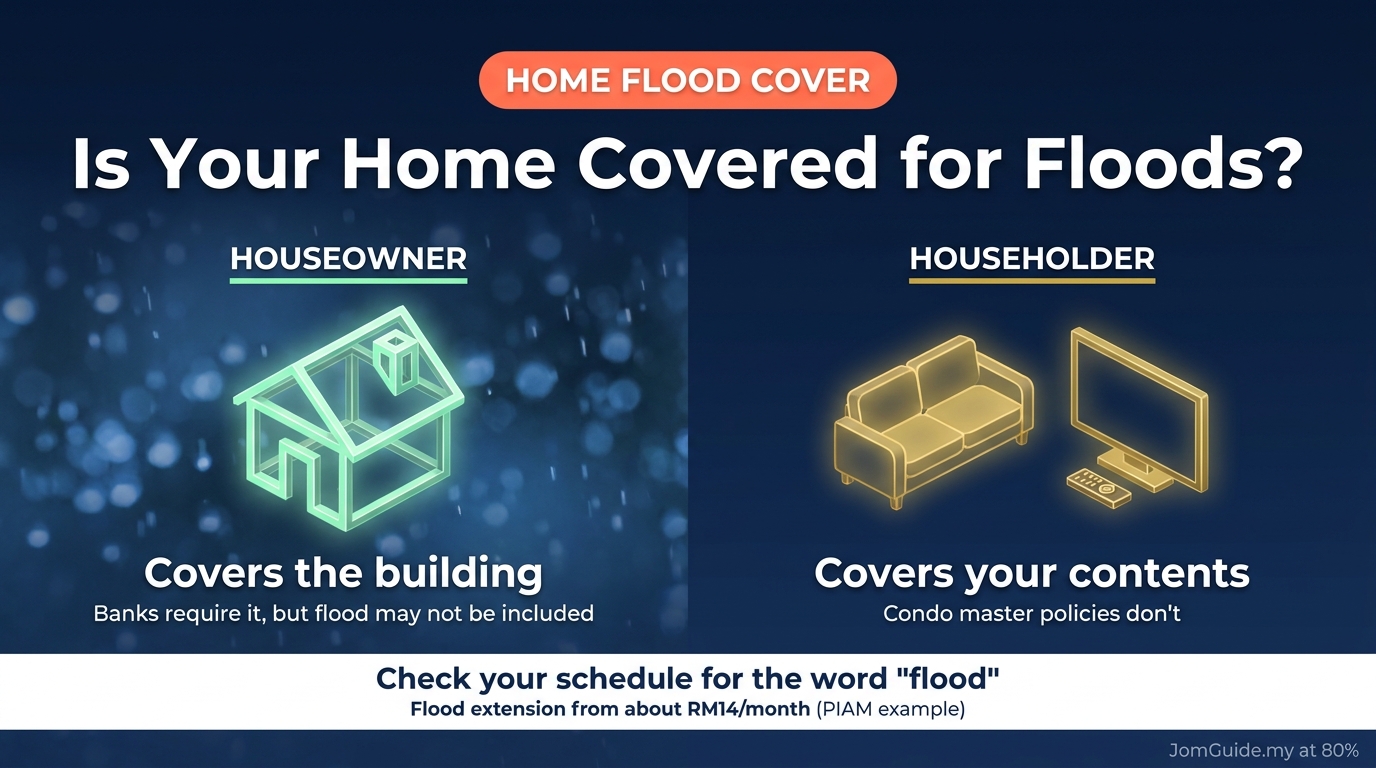
Source: Source: PIAM, Tokio Marine, money.com.my (Oct 2026)
The short answer: whether you're paid for a flooded home depends on whether your policy includes flood cover. Many owners assume the fire policy their bank required covers them, but according to the General Insurance Association of Malaysia (PIAM), a basic fire policy often excludes floods unless you add an extension. Condo owners should also know that the management's master policy doesn't cover your furniture or renovations.
After this week's Klang Valley flash floods, now is a good time to dig out your policy.
Two kinds of home insurance
| Houseowner (building) | Householder (contents) | |
|---|---|---|
| What it covers | The structure: walls, roof, wiring, plumbing, fixed fittings | Movable items: furniture, electronics, clothing |
| Required by banks? | Usually, for the life of the mortgage | No, it's optional |
| How claims are paid | Based on rebuilding cost | Mostly on depreciated value |
MRTA and MLTA are not home insurance. They are life cover on the borrower that pays off the loan, not cover for the building.
Is flood included?
- Basic fire policy: PIAM says these often exclude flood, windstorm and earthquake unless extended for an extra premium.
- Houseowner/Householder policies: wording varies. Some insurers list flood as standard; others need an extension. The only reliable check is your policy schedule. Look for the word "flood".
- It's not expensive: PIAM says adding flood to a fire policy can cost as little as about RM14 a month for a building insured at RM200,000.
- Landslides are usually separate. Many policies exclude landslip and subsidence or offer them only as an add-on.
JomGuide's advice: if you live in a low-lying area or your home has flooded before, add flood cover. Plenty of homeowners, the JomGuide team included, have only the fire policy their bank asked for and never look at it again. If your area floods, a few minutes checking is well worth it.
Condo owners: what you need to cover yourself
Your JMB or MC buys a master policy funded by maintenance fees. It usually:
- covers the building structure and common property;
- doesn't cover your unit's contents, renovations beyond the original condition (custom cabinets, for example) or liability for leaks from your unit.
If you're on a low floor or park in a basement, consider your own Householder policy for your belongings.
Watch out for the average clause
If you insure for less than the actual rebuilding cost, the insurer pays only a proportion of your claim.
Example: your home costs RM400,000 to rebuild but is insured for RM250,000. A RM100,000 flood loss may be settled at:
RM100,000 × (250,000 ÷ 400,000) = RM62,500
Set your sum insured on rebuilding cost, not market value or your loan amount. PIAM's website has a building cost calculator to help.
How to claim after a flood
- Stay safe. Return only after the water recedes, and switch off the mains before going in.
- Photograph and film everything before cleaning up, including the water line on the walls.
- Notify your insurer promptly. Most policies set a reporting deadline.
- Don't throw damaged items away yet. A loss adjuster may need to see them.
- Get written approval before repairs. Unauthorised repairs may not be covered; keep receipts for emergency work.
- Prepare your documents: claim form, photos, an itemised inventory (brand, model, purchase date) and repair quotes.
Simple claims are usually settled quickly; complex ones can take 8 to 12 weeks, and some insurers offer interim payments for urgent repairs.
A flooded car is covered by a separate policy. See Car Flood Insurance Malaysia.
FAQ
I have the fire policy my bank required. Am I covered for floods?
Not necessarily. Basic fire policies often exclude flood. Check whether your schedule lists it.
I live on a high floor of a condo. Do I need flood cover?
Your unit is unlikely to flood, but think about your car in the basement car park and water damage from leaks.
Can tenants buy home insurance?
Yes, a Householder policy for your own belongings. The building is the landlord's responsibility.
How much does flood cover cost?
PIAM's example is about RM14 a month for a building insured at RM200,000. Actual premiums depend on location, sum insured and insurer, so compare at least three quotes.
This is general information, not insurance advice. Your cover depends on your policy wording.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.
Related articles
More in Jom Money-
Driving Into Singapore From 2027: VEP Rises to S$50 a Day, Free Days and Evening Hours Scrapped. Here's What It Costs You
-
STR 2026 Phase 4 Is Being Paid: Up to RM500 for Households, RM150 for Seniors, 4–6 November, New Recipients From the 16th
-
When Is STR 2026 Phase 4 Paid? Not Announced Yet: What You Can Do Now, Plus STR 2027 Applications