Car Flood Insurance Malaysia: Special Perils Cover, Claim Steps and Repair Costs
Flooded car in Malaysia? Standard comprehensive insurance may exclude the damage. Learn how to check Special Perils, notify your insurer, arrange towing and make a claim.

Source: PIAM flood claims notices and motor insurance guidance; MSIG flood advisory
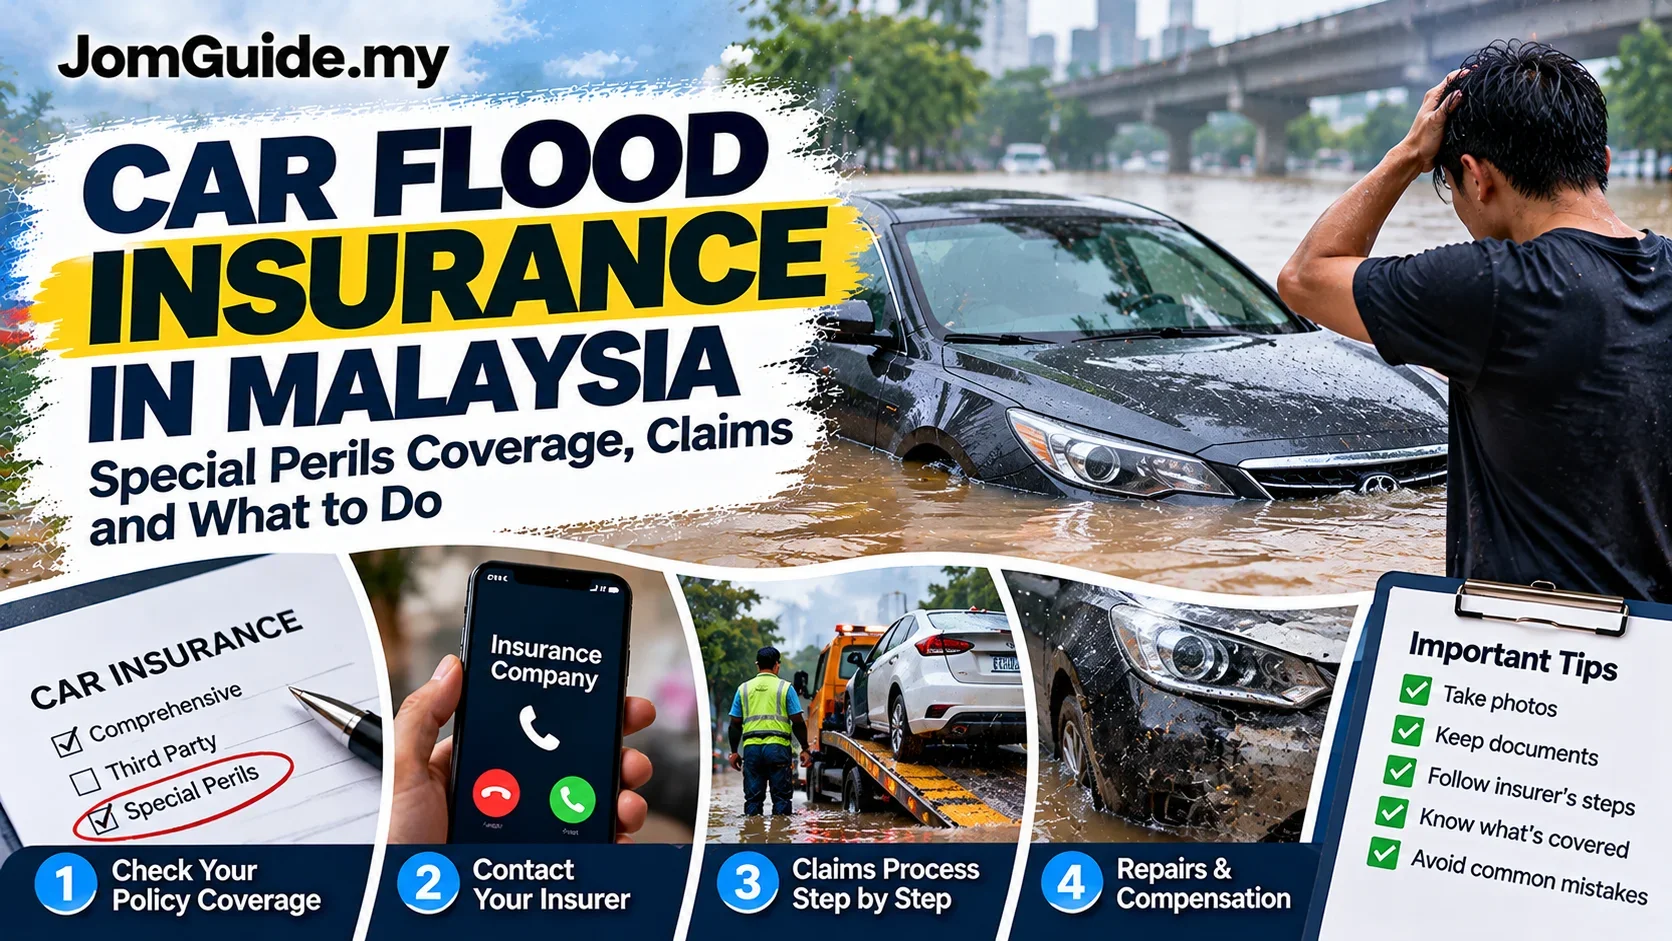
Checked on 16 October 2026. If a Malaysian car is damaged by floodwater, a comprehensive motor policy does not automatically mean the damage is insured. Standard comprehensive coverage generally excludes flooding unless relevant Special Perils / flood cover has been added and the loss meets the applicable conditions.
What happens after the water recedes matters just as much as what you bought at renewal. This guide focuses on checking coverage, making a claim and understanding possible costs, rather than general rainy-season preparation.
Does comprehensive car insurance cover floods?
Malaysia's General Insurance Association, PIAM, explains that a standard comprehensive motor policy typically does not insure loss or damage from floods. An additional extension may be available.
| Policy situation | What it generally means | Next action |
|---|---|---|
| Comprehensive without flood extension | Do not assume flood repairs will be covered | Ask your insurer about the precise wording and any assistance available |
| Comprehensive with Special Perils / flood protection | The loss may be claimable, subject to terms | Notify your insurer and follow its assessment process |
| Unsure of your cover | The label 'full insurance' proves little | Check the Additional Coverage section of your policy schedule |
Special Perils isn't a blank cheque: insured value, exclusions, limits, excess and the circumstances of damage still matter. See PIAM's official flood claims and cover explanation.
Car flooded? Do these things in a sensible order
Safety comes first. Do not wade through moving or unknown-depth floodwater to reach a vehicle or take photographs. If the car has been flooded, avoid trying to restart a potentially water-damaged engine; additional damage can result. Seek help from a safe place.
1. Contact your insurer or takaful operator promptly. Use the official hotline shown on your policy. Describe when and where the flood happened and ask whether towing or a designated workshop can be arranged.
2. Verify the policy. Find your policy schedule or takaful certificate. Check the Flood / Special Perils extension, insured amount, excess, exclusions and any claims notification period.
3. Document the incident, only when safe. Note the vehicle registration, location, date, water marks, visible damage and any recovery costs. Photos and videos can help, but never at the cost of personal safety.
4. Follow the towing and repair instructions. Ask before authorising an independent towing company or major repairs. The insurer may appoint a loss adjuster or refer you to a panel workshop.
5. Submit documents and follow up. Provide the information the insurer requests. Ask for a claim reference and keep copies of estimates, invoices and messages.
PIAM's flood claims guidance confirms the key sequence: check cover, notify the insurer, provide relevant documents and cooperate with an adjuster if appointed.
What documents might you need?
Requirements differ by insurer and the scale of the damage. Prepare what you can:
- Policy or certificate number and vehicle registration.
- Owner's identification and contact details.
- Time, place and explanation of the flooding.
- Safe-to-capture photos or videos of the damage.
- Official towing records, repair quotations and receipts.
- Any further forms or reports your insurer requests.
Is a police report always compulsory? Don't assume so. Some insurers waive it for certain flood claims. For example, MSIG's flood advisory outlines a specific waiver for qualifying policyholders. That does not create a uniform rule across Malaysia. Ask your own provider.
What if you never bought Special Perils?
You should generally not budget on a standard comprehensive policy paying for flood-related repairs when flood cover is absent. Your insurer can clarify whether any separate assistance applies, including towing or special measures, but assistance and insurance compensation are not the same thing.
Three questions to ask on the call:
- Is this specific flood loss covered by my policy and endorsements?
- If not covered, do I have roadside assistance, and what would it cost?
- Where should the vehicle be assessed and what evidence should I retain?
Even when a provider offers complimentary towing during a flood event, it does not mean it has accepted a claim for the damage.
Repair bills, payout amounts and timing
These are three separate issues—not one predictable number.
Repair costs depend on the depth and duration of flooding, condition of the vehicle, affected electronics, parts and repair plan. A viral RM figure from another owner is not a reliable quote.
Claims payouts depend on what is insured and on the insurer's assessment. The sum insured is not an automatic payment merely because water entered a vehicle. Ask about excess, limitations, repair versus total-loss assessment, and any expenses you would still bear.
Claim timelines can vary with inspections, supporting information, workshop capacity and claim complexity. PIAM notes that some insurers may expedite claims, but you should not treat a special arrangement or online anecdote as a universal payout deadline.
A useful approach: request a written breakdown of what is covered, what isn't, your possible contribution and the next review date.
Should I buy flood insurance when renewing?
Check your policy schedule, not just the marketing label. Locate Additional Coverage / Endorsements, verify Flood / Special Perils, and ask about limits, exclusions and how the insurer handles flooded vehicles.
PIAM's motor insurance comparison guide notes that flood is normally an additional protection rather than an automatic feature of standard comprehensive cover.
Premiums depend on the vehicle and product. This guide does not invent a universal price or promise that every insurer will approve the same claim.
Frequently asked questions
Does 'full coverage' guarantee flood compensation?
No. You need to verify the actual policy and any Special Perils extension.
If I bought Special Perils, will I receive my whole insured value?
Not automatically. Terms, limits and the loss assessment determine the outcome.
If I don't restart the engine, does that guarantee a claim?
No. It is a sensible damage-prevention precaution, not a substitute for insurance cover.
Can I arrange any tow truck and claim it back?
Ask your insurer first. Approved networks, reimbursement terms and receipts vary between policies.
Can I purchase flood cover after my vehicle has already flooded?
Newly purchased cover generally cannot be used to insure a loss that happened before it took effect.
The practical JomGuide point: treating 'comprehensive' as a synonym for 'covers everything' is an expensive mistake. Confirm the endorsement before trouble starts; if flooding occurs, put safety first and follow your own provider's claim instructions.
For preparation before heavy rainfall, read the Malaysia Flash Flood Guide.
Sources
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.