First Home Stamp Duty 2027: How Much Can RM500k, RM650k and RM750k Buyers Save?
Budget 2027 proposes extending first-home stamp-duty relief to properties up to RM750,000. Compare estimated transfer-duty savings on RM500k, RM650k, RM750k and RM800k homes plus 90% financing examples.

Source: PMO Budget 2027 (9 Oct 2026); LHDN stamp-duty guidance; Budget 2026 tax appendix
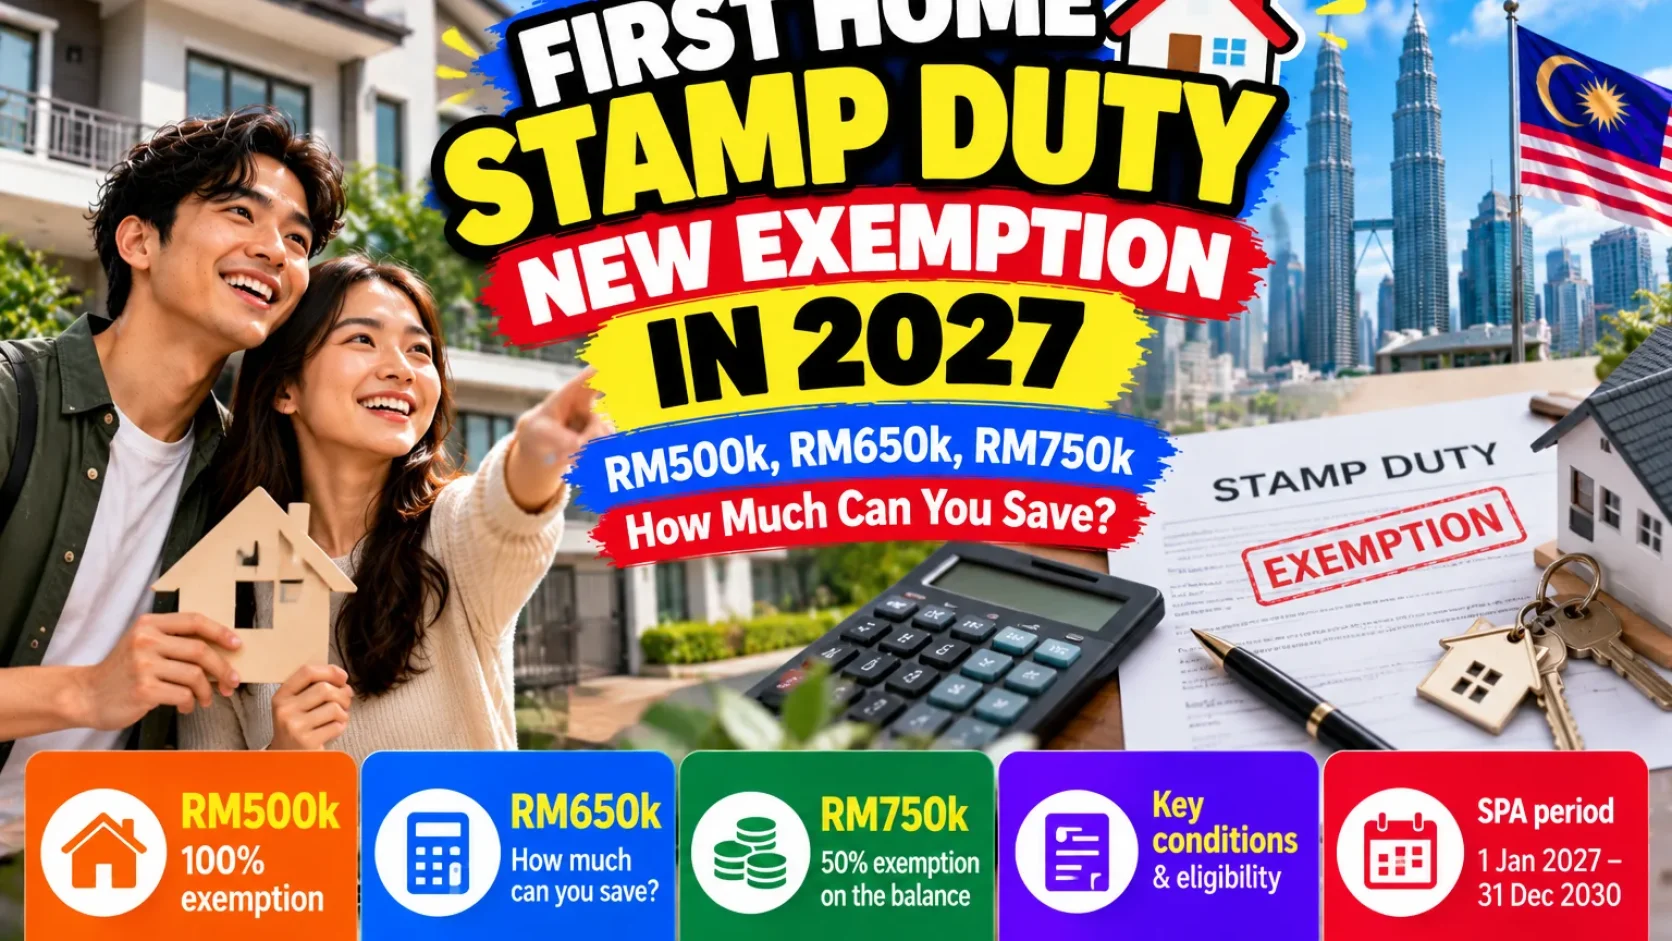
Budget 2027 proposed full stamp-duty exemption on the first RM500,000 of a qualifying first residential home, with a 50% exemption on the remainder for homes priced up to RM750,000. The proposal covers transfer instruments and loan agreements and refers to qualifying sale and purchase agreements signed from 1 January 2027 through 31 December 2030.
A RM750,000 home is not entirely stamp-duty-free. This is an announced proposal, not an already-operative October 2026 entitlement. The final exemption order and legal advice determine actual eligibility. See the official Budget speech.
Estimated transfer stamp duty: four home prices
The ordinary residential transfer-duty bands used here are 1% on the first RM100,000, 2% on the next RM400,000, and 3% on the next RM500,000. This simplified estimate assumes the property value used for duty equals the advertised purchase price, the buyer qualifies, and the proposed relief takes effect as described.
| House price | Ordinary transfer duty | Indicative saving under proposal | Indicative duty payable |
|---|---|---|---|
| RM500,000 | RM9,000 | RM9,000 | RM0 |
| RM650,000 | RM13,500 | RM11,250 | RM2,250 |
| RM750,000 | RM16,500 | RM12,750 | RM3,750 |
| RM800,000 | RM18,000 | RM0 under this specific proposal | RM18,000 |
This table covers the transfer instrument only. Loan-agreement duty after exemption, lawyer fees, valuation, insurance and all other purchase costs are not included.
How the RM650,000 example works
Ordinary duty is RM1,000 on the first RM100k, RM8,000 on the next RM400k, and RM4,500 on the remaining RM150k: total RM13,500. Under the proposed formula, the duty related to the first RM500k (RM9,000) is exempt, plus half of RM4,500, giving RM11,250 indicative saving and RM2,250 remaining duty.
Why a RM750,000 home is not fully exempt
Ordinary transfer duty is RM9,000 on the first RM500k plus RM7,500 on the additional RM250k. The additional portion would receive 50% relief, leaving an indicative RM3,750 payable.
What about RM800,000?
That price is above the proposed RM750,000 property price ceiling. This specific announced first-home relief should not be presumed to apply; any other qualifying exemption would need separate verification.
What if the buyer takes a 90% home loan?
To distinguish the two documents, use 90% financing, with the ordinary pre-relief loan-agreement stamp-duty baseline estimated at 0.5% of the loan amount.
| Property | Assumed 90% loan | Ordinary loan duty before relief |
|---|---|---|
| RM500,000 | RM450,000 | RM2,250 |
| RM650,000 | RM585,000 | RM2,925 |
| RM750,000 | RM675,000 | RM3,375 |
| RM800,000 | RM720,000 | RM3,600 |
The Budget proposal also refers to loan agreements. However, the exact legal application of partial relief to different loan amounts and documentation must be checked once the formal order is issued. That is why these are before-exemption baselines, not definitive final loan-duty amounts.
Is this already valid for a SPA signed in 2026?
Do not assume so. A Budget 2026 tax appendix extended the existing full exemption for qualifying first homes up to RM500,000 for SPAs executed in 2026–2027. The new 2027 proposal extends and broadens relief through 2030 and includes the higher price band. The date of the SPA matters.
Stamp-duty exemption is not mortgage-interest tax relief
Stamp-duty exemption reduces applicable one-off document tax. Housing-loan interest tax relief is a separate potential income-tax deduction, subject to its own conditions. It does not erase the interest charged by a bank.
For the existing RM500,000 example and a discussion of the other upfront costs, read JomGuide's First RM500k Home: Stamp Duty vs Housing Loan Tax Relief.
Before signing, check five things
- Your first-home and citizenship eligibility under the final order.
- The SPA date and effective policy period.
- Property price and the actual value used for stamp-duty assessment.
- Whether both transfer and financing documents satisfy the conditions.
- A lawyer's document-by-document fee breakdown using the rules in force.
FAQ
Is duty halved for an entire RM650k house?
No. The proposal exempts the first RM500k fully and half of the duty on the remaining part.
Is a RM750k house fully exempt?
No. Relief on the amount above RM500k is only partial under the announcement.
Does a RM800k first home automatically get partial relief?
No; it is above the proposed ceiling for this particular scheme.
Can I claim the new RM750k relief for a 2026 SPA?
The new announced proposal specifies SPAs from 1 January 2027, subject to implementation.
Do these savings include lawyer fees?
No. They are illustrative transfer-duty figures.
Bottom line
Treat the numbers as an early planning guide, not a final legal calculation. Verify the enacted relief and your transaction details before committing to a property purchase.
Sources: Budget 2027 · LHDN stamp duty overview · LHDN exemptions · Budget 2026 tax measures
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.