PTPTN 2027: RM2,500 Deferment, RM50 Repayments and 10% Discount Explained
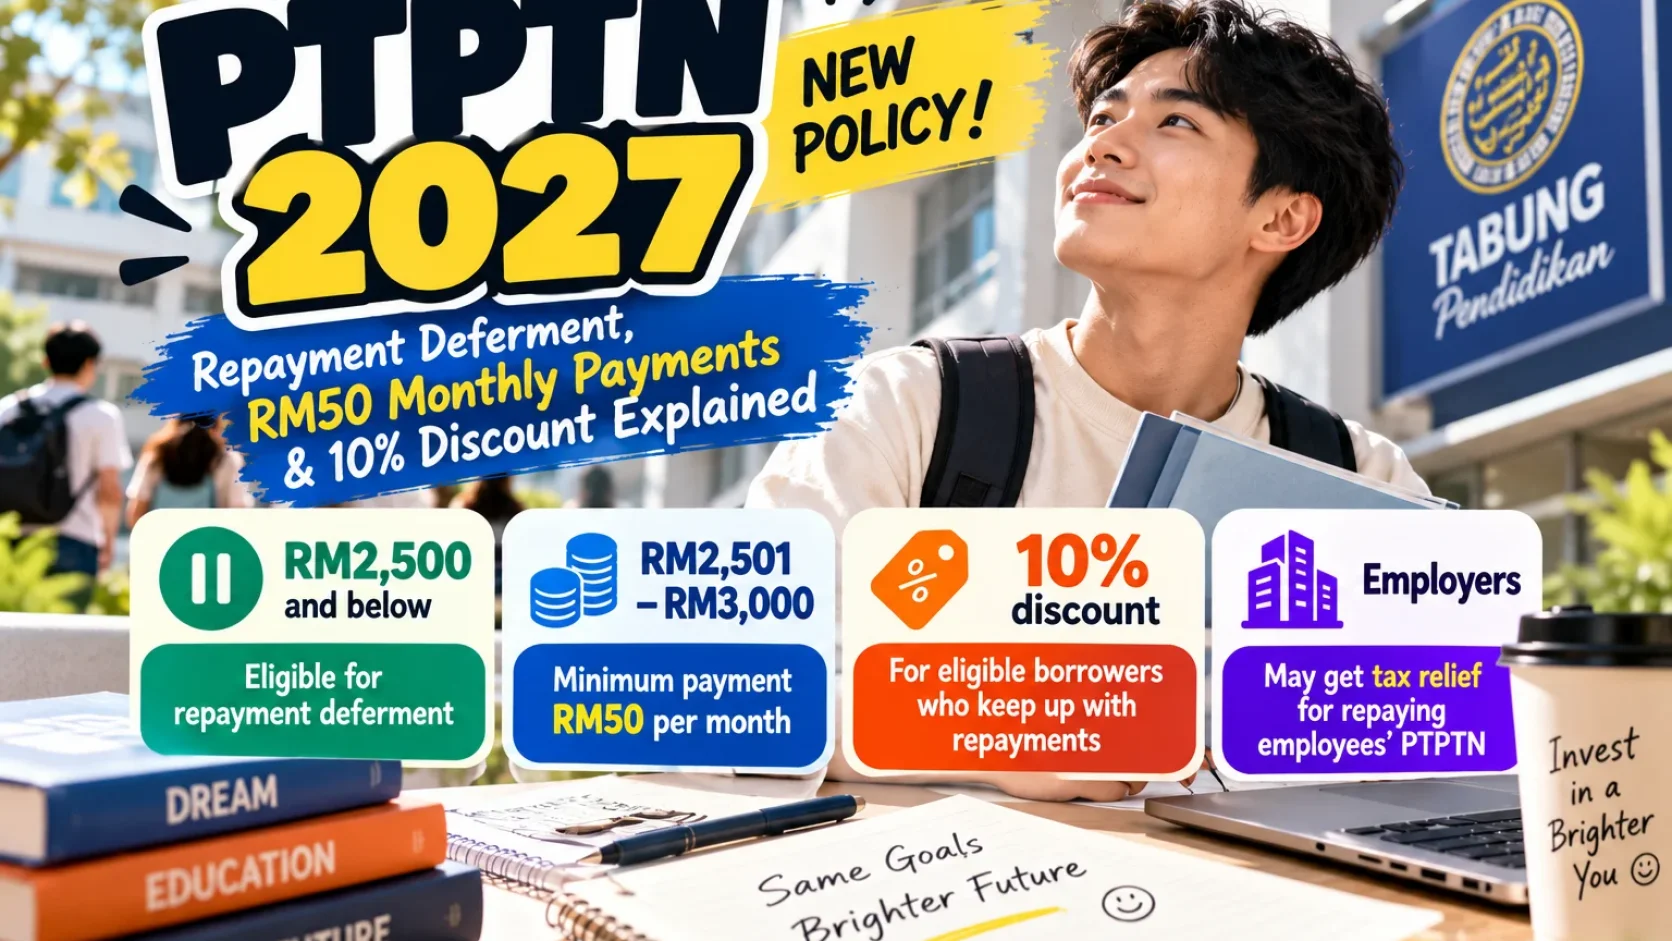
PTPTN announced 2027 repayment deferment for borrowers earning up to RM2,500, a minimum RM50 payment for RM2,501–RM3,000 earners, and a conditional 10% discount. See five salary examples and next steps.

Source: PTPTN official statement (11 Oct 2026); MOF Budget 2027 speech (9 Oct 2026)
PTPTN's 2027 measures are not a blanket loan write-off. The official PTPTN announcement dated 11 October 2026 confirms three central proposals for 2027: repayment deferment for borrowers earning up to RM2,500 per month; a RM50 minimum monthly repayment for borrowers earning RM2,501–RM3,000; and a 10% discount for qualifying active borrowers who have no arrears and consistently repay.
The 2027 application process, implementation date and exact calculation of the discount are not fully published. Do not stop existing repayments based on the headline alone.
Which income band applies to you?
| Illustrative monthly income | Announced 2027 measure | Important caveat |
|---|---|---|
| RM2,000 | Within the up-to-RM2,500 deferment range | Deferment does not cancel the loan |
| RM2,500 | Still within the deferment range | Exactly RM2,500 differs from RM2,501 |
| RM2,800 | Falls in RM2,501–RM3,000 RM50 minimum band | Individual approval and formal rules still matter |
| RM3,000 | Upper limit of the announced RM50 band | No automatic deletion of past arrears |
| RM3,500 | Outside both announced income bands | Existing PTPTN restructuring options may still be relevant |
PTPTN states that income information will be cross-checked with LHDN. The calculation for fluctuating self-employed income or a recent job loss requires implementation guidance.
Deferment does not mean forgiveness
Penangguhan is a postponement of repayment. Penghapusan hutang would mean eliminating an obligation; that has not been announced for everyone here.
For example, if you currently owe RM12,000, qualifying for deferment does not automatically make that balance RM0. The formal rules must explain how long the relief lasts, applicable charges and account reporting.
Until a new arrangement is formally approved, do not unilaterally cancel direct debit or reduce agreed payments.
What does "RM50 minimum" actually mean?
For incomes of RM2,501–RM3,000, the announcement specifies a minimum repayment of RM50. That does not mean the whole loan can be discharged by one RM50 payment. Repayment periods, outstanding charges and the revised Jadual Bayaran Balik (JBB) depend on official processing.
A borrower earning RM2,800 may benefit from a lower monthly obligation, but should also understand the repayment term and longer-run total payments.
Who gets the 10% discount?
The confirmed target group is active PTPTN borrowers without arrears who make regular, consistent repayments. The 11 October statement does not yet establish whether the 10% applies to each instalment, particular repayment periods or another defined amount, or whether there are monetary caps.
| Situation | What to conclude |
|---|---|
| Current payments, no arrears | You fit the announced broad target description; check final rules |
| Historical arrears | Do not presume the 10% discount applies |
| Lump-sum settlement | Do not assume this is a separate 10% settlement discount |
| Irregular payment pattern | Review your repayment history with PTPTN |
Avoid making a large payment solely because a headline mentions 10%.
What about existing tunggakan (arrears)?
The new Budget announcement does not say historical arrears disappear automatically.
Check four pieces of information in your account:
- Outstanding balance: the full amount still owed.
- Tunggakan: overdue instalments.
- JBB: currently approved repayment schedule.
- Your loan category and any existing rescheduling, restructuring or deferment arrangement.
Our earlier guide covers the existing rescheduling, restructuring and deferment processes, including circumstances where part of arrears must first be paid: JomGuide PTPTN Restructuring Explained. That separate process should not be confused with the new 2027 income-based announcement.
How to prepare and check with myPTPTN
- Start at the official PTPTN repayment portal and log in through myPTPTN.
- Review your current JBB, account balance, overdue amounts and payment records.
- Keep income information and payslips ready; PTPTN says LHDN cross-checks will apply.
- Follow PTPTN's official 2027 updates for exact activation dates, application forms, qualification rules and discount calculations.
- If you cannot afford your current instalment, contact PTPTN now about the current relief options rather than waiting for 2027.
Employer assistance: qualifying employers who repay workers' PTPTN loans between 1 January 2027 and 31 December 2028 may receive a tax deduction under the announced measure. That does not mean all workers receive employer-paid PTPTN.
FAQ
Can RM2,500 earners stop paying now?
No. The new initiative is for 2027 and requires formal implementation and personal verification.
Is RM50 automatically my payment if I earn RM2,800?
It is the announced minimum for the income category, subject to official rules and account arrangements.
Does 10% reduce my whole balance?
The published announcement does not establish that. Do not assume it.
Are old arrears forgiven?
No such general forgiveness was announced.
What if income is irregular?
Wait for official income definitions and verification procedures.
JomGuide's view
The point is not simply a lower number on a news headline. It is a manageable, officially approved payment schedule that does not create new arrears by mistake. Confirm your actual terms before changing payments.
Official sources: PTPTN 2027 announcement · MOF Budget 2027 · PTPTN repayment portal
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.