Buying Your First RM500k Home? Stamp Duty Exemption and Housing Loan Tax Relief Explained
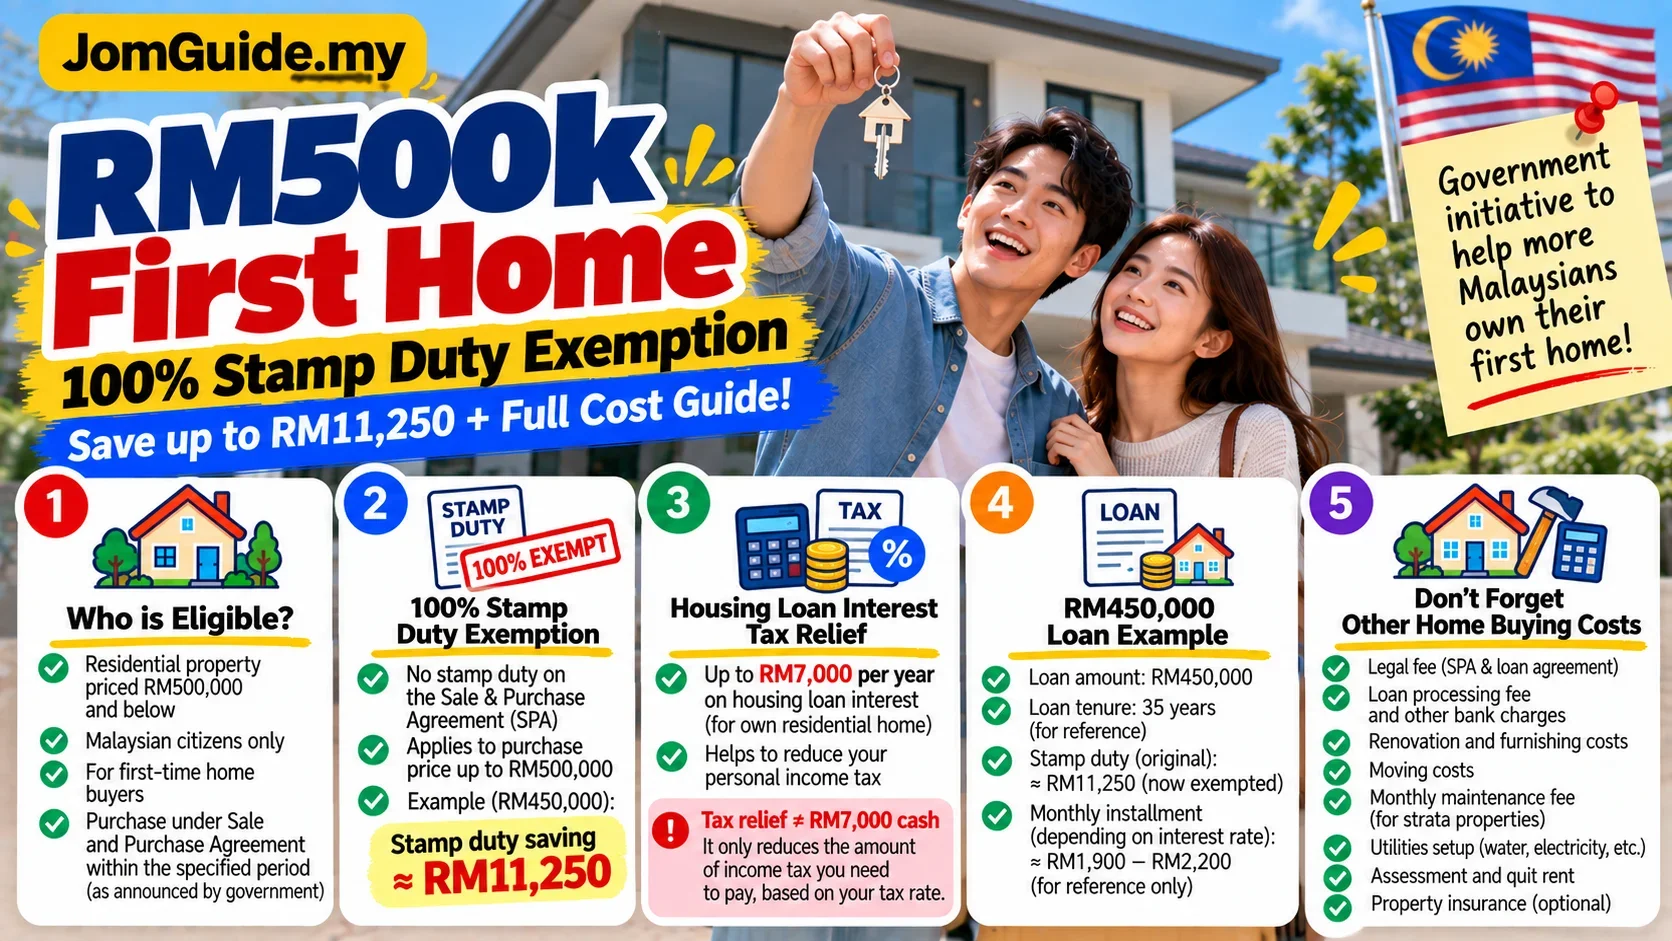
A first RM500k home is not just about the monthly instalment. Eligible Malaysian first-home buyers can receive a 100% stamp-duty exemption in 2026–2027, while a separate housing-loan interest tax relief can be worth up to RM7,000 a year.

Source: Source: MOF Budget 2026 tax measures; HASiL tax relief guidance and Public Ruling 7/2025
First-time buyers often focus on one number:
the monthly instalment.
But before signing an SPA, the budget should also include:
- stamp duty;
- legal fees;
- loan-related costs;
- insurance or takaful;
- renovation and moving;
- maintenance;
- utilities and other recurring ownership costs.
For qualifying Malaysian first-home buyers, two benefits are especially important in 2026–2027:
- 100% Stamp Duty Exemption
- Housing Loan Interest Tax Relief
They are completely different benefits.
A RM500,000 example
Assume:
- property price: RM500,000
- Malaysian citizen;
- first qualifying residential home;
- SPA signed within the eligible 2026–2027 exemption period;
- 90% financing = RM450,000 loan.
The 90% financing assumption is only for illustration.
Benefit 1: 100% stamp duty exemption
Budget 2026 extended the first-home stamp-duty exemption.
For a Malaysian citizen buying a first residential home priced at RM500,000 or below, qualifying:
- instrument of transfer; and
- loan agreement
receive a 100% stamp-duty exemption for SPAs executed from:
1 January 2026 to 31 December 2027.
What would the transfer stamp duty normally be on RM500k?
The property-transfer stamp-duty bands are:
- first RM100,000: 1%
- RM100,001–RM500,000: 2%
So:
First RM100,000
RM100,000 × 1% = RM1,000
Next RM400,000
RM400,000 × 2% = RM8,000
Transfer stamp duty
RM9,000
For a qualifying first-home purchase under the full exemption, that amount is exempted.
What about the loan agreement?
Residential loan-agreement stamp duty is generally:
0.5% of the loan amount
With a RM450,000 loan:
RM450,000 × 0.5% = RM2,250
For a qualifying first-home purchase, this is also covered by the full exemption.
Total stamp-duty saving in this example
| Item | Normal stamp duty | After qualifying exemption |
|---|---|---|
| Property transfer | RM9,000 | RM0 |
| RM450k loan agreement | RM2,250 | RM0 |
| Total | RM11,250 | RM0 |
So under this specific 90%-loan example, the stamp-duty saving is about:
RM11,250
The actual number changes with the loan amount.
Stamp-duty exemption does not mean buying the home has no upfront costs
The exemption covers qualifying stamp duty.
It does not automatically remove:
- lawyer or solicitor professional fees;
- loan legal work;
- valuation costs;
- insurance/takaful;
- disbursements;
- deposits;
- renovation;
- moving costs;
- other project-specific charges.
Do not build your cash budget around the down payment alone.
Benefit 2: housing-loan interest tax relief
This is separate from stamp duty.
HASiL currently provides first-residential-property housing-loan interest relief for qualifying SPAs signed between:
1 January 2025 and 31 December 2027
The limits are:
Property price up to RM500,000
Up to:
RM7,000 a year
Above RM500,000 up to RM750,000
Up to:
RM5,000 a year
For this RM500k example, the relevant limit is RM7,000.
RM7,000 relief does not mean RM7,000 cash
This is critical.
Tax relief is not a cash rebate.
It reduces taxable income.
If you pay RM6,000 of qualifying housing-loan interest in a year, your claim is based on the actual qualifying amount, not an automatic RM7,000 payment.
If qualifying interest is RM10,000, the relief is capped at RM7,000.
How much tax you ultimately save depends on your taxable income and applicable tax rate.
How many years can you claim it?
HASiL's Public Ruling examples explain that the relief can apply for three consecutive Years of Assessment, beginning from the YA in which qualifying interest is first paid.
For example, if an eligible SPA is signed in 2027 but loan interest only starts in 2028, the three-year relief period can begin from YA 2028, subject to all conditions.
It is not a permanent annual RM7,000 relief.
Conditions worth checking before signing
Current HASiL guidance highlights that the relief is for:
- the first residential property;
- purchased to be occupied as a residence;
- limited to one unit;
- an SPA within the qualifying period;
- qualifying housing-loan interest actually paid.
If you already have property ownership, joint ownership or a special ownership arrangement, confirm whether you satisfy the first-residential-property definition before assuming the relief applies.
Stamp duty exemption vs housing-loan interest relief
| Stamp Duty Exemption | Housing Loan Interest Relief | |
|---|---|---|
| When it matters | Property transaction | Income-tax filing |
| RM500k qualifying home | 100% transfer + loan stamp-duty exemption | Up to RM7,000 qualifying interest/year |
| Cash payout? | No | No |
| Reduces loan principal? | No | No |
| Main timing | SPA 2026–2027 | SPA 2025–2027 + interest conditions |
The simplest distinction is:
Stamp-duty exemption reduces a transaction tax.
Housing-loan interest relief reduces taxable income when you file taxes.
How do you claim the housing-loan interest relief?
When filing individual income tax, claim the qualifying first-home housing-loan interest under the applicable tax-relief section.
Keep supporting records such as:
- SPA;
- loan agreement;
- bank annual loan or interest statement;
- proof of interest paid;
- relevant ownership documents.
HASiL generally requires taxpayers to retain supporting records for seven years for review purposes.
Do not claim the entire monthly instalment as interest.
A housing-loan payment contains:
- principal; and
- interest.
The relief applies to qualifying interest paid.
Do not look only at the instalment
A bank telling you that the monthly instalment is affordable is only one part of the decision.
Also ask:
- How much emergency cash remains after the down payment?
- Are legal, loan and valuation costs included?
- How much will renovation cost?
- Is there maintenance or sinking fund?
- What will water, electricity, internet and other recurring bills add?
- Can the instalment change if financing rates move?
- Is there a repair buffer?
Owning a home creates costs that continue after the SPA is signed.
Bottom line for a RM500k first home
With a qualifying first-home purchase and a RM450k loan:
Illustrative stamp-duty saving: about RM11,250
Separately, a qualifying buyer may claim:
up to RM7,000 of housing-loan interest relief per year for up to three consecutive YAs, subject to the rules.
But the most important budgeting rule is still:
do not judge the home only by the monthly instalment — include legal, financing, moving and ongoing household costs before signing.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.