第一次买 RM500k 房子能省多少?Stamp Duty Exemption + Housing Loan Interest Relief 一次算
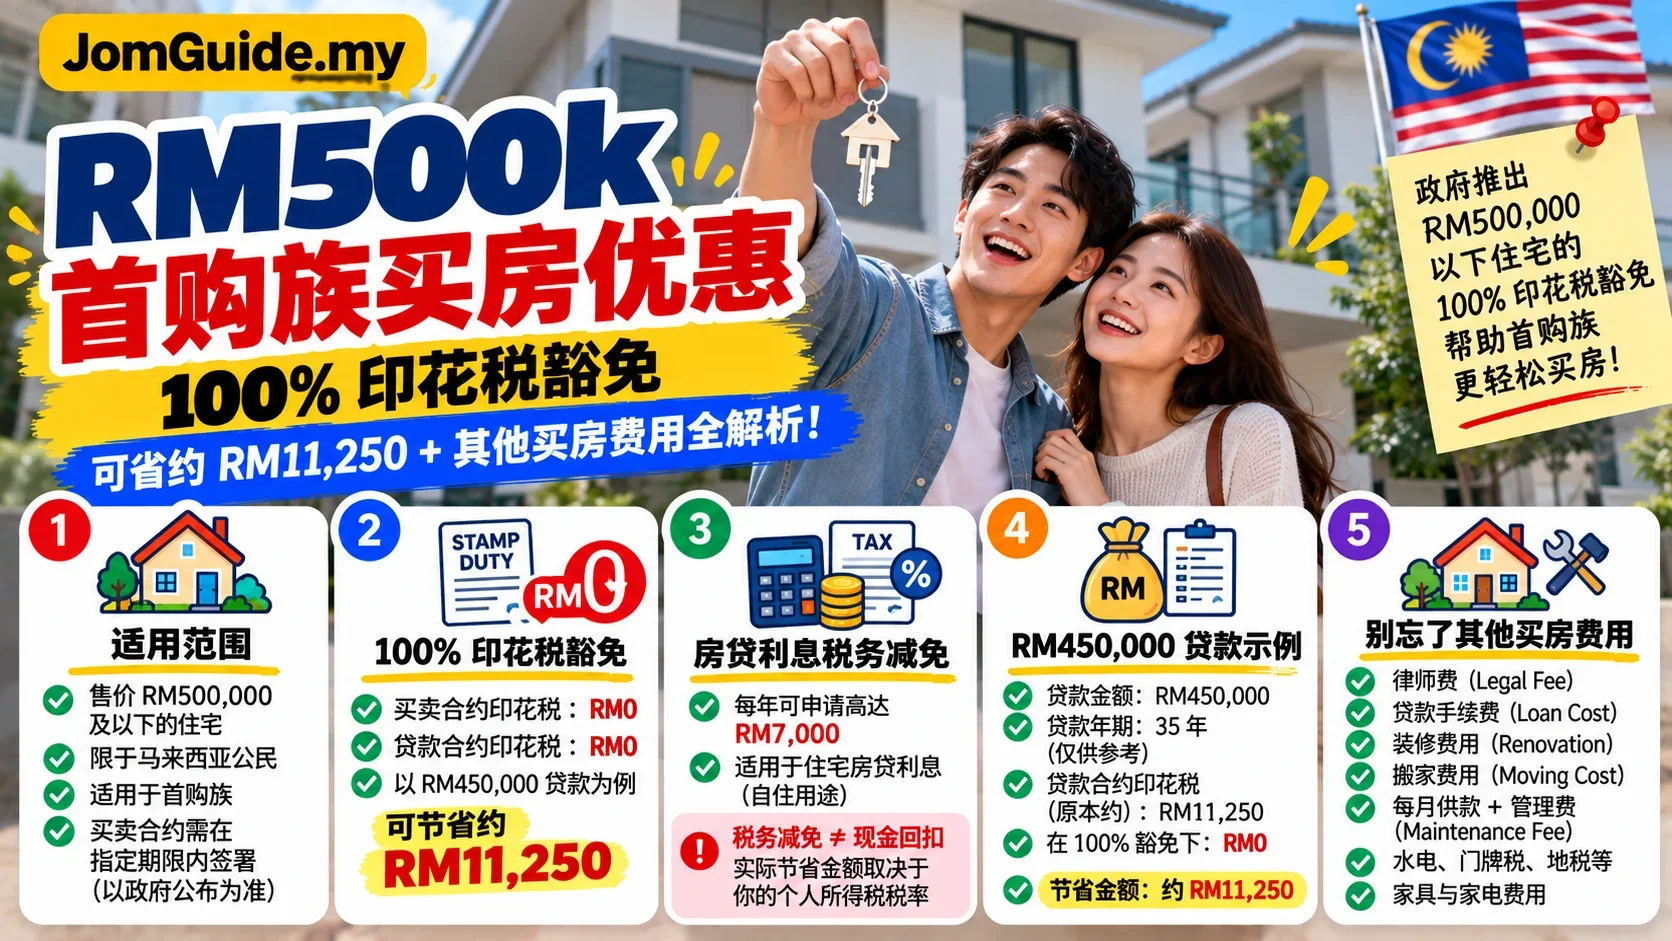
第一次买 RM500k 房子,不要只看月供。符合条件的 Malaysian first-home buyer 在 2026–2027 可享 transfer 和 loan agreement 100% stamp duty exemption;另外还有最高 RM7,000 housing-loan interest tax relief,但两者完全不是同一件事。

来源: Source: MOF Budget 2026 tax measures; HASiL tax relief guidance and Public Ruling 7/2025
第一次买房,很容易只盯着一个数字:
“月供多少?”
但真正签 SPA 前,应该一起看的还有:
- stamp duty;
- lawyer / legal fee;
- loan-related cost;
- insurance / takaful;
- 装修与搬家;
- maintenance;
- 水电、internet 等入住后的固定开销。
2026–2027 对符合条件的 Malaysian first-home buyer 来说,有两项特别值得分清楚的 benefit:
- 100% Stamp Duty Exemption
- Housing Loan Interest Tax Relief
这两个常常被讲成同一件事,其实完全不同。
先用一个 RM500,000 First Home 例子
假设:
- 房价:RM500,000
- Malaysian citizen
- 第一次购买 residential home
- SPA 在符合 exemption 的 2026–2027 period 内签署
- Housing loan:假设 90% financing = RM450,000
这是一个方便理解的 example,不代表每个人的 loan structure 都一样。
Benefit 1:100% Stamp Duty Exemption
Budget 2026 的 official tax measure 延长了 first-home stamp duty exemption。
对于 Malaysian citizen 第一次购买价格 RM500,000 或以下的 residential property:
Instrument of Transfer + Loan Agreement 都可享 100% stamp duty exemption
适用于 SPA 在:
1 January 2026 – 31 December 2027
执行的 qualifying purchase。
RM500k 房子的 Transfer Stamp Duty 原本多少?
Malaysia residential property transfer stamp-duty rate:
- First RM100,000:1%
- RM100,001–RM500,000:2%
所以 RM500,000:
First RM100,000
RM100,000 × 1% = RM1,000
Next RM400,000
RM400,000 × 2% = RM8,000
Total Transfer Stamp Duty
RM9,000
如果符合 first-home 100% exemption:
这一部分理论上省 RM9,000。
Loan Agreement Stamp Duty 又是多少?
Housing loan agreement 的 stamp duty 通常按:
0.5% × loan amount
如果这个 RM500k 房子用 90% financing:
Loan amount = RM450,000
RM450,000 × 0.5% = RM2,250
符合 first-home exemption 的情况下,这部分也获得 100% exemption。
这个 RM500k Example,总 Stamp Duty 大约省多少?
在我们假设 90% loan 的情况下:
| 项目 | 原本 Stamp Duty | Exemption 后 |
|---|---|---|
| Property Transfer | RM9,000 | RM0 |
| RM450k Loan Agreement | RM2,250 | RM0 |
| Total | RM11,250 | RM0 |
所以这个 specific example 下,stamp duty saving 大约:
RM11,250
但这个数字不是所有 RM500k buyer 都一样,因为 loan agreement stamp duty 会跟实际 loan amount 变化。
例如你不是借 90%,数字就会不同。
但 Stamp Duty Exemption 不代表买房“没有 upfront cost”
这是第一次买房最容易误会的地方。
被 exemption 掉的是 qualifying stamp duty。
不代表以下全部免费:
- lawyer / solicitor professional fee;
- loan legal work;
- valuation fee;
- insurance / takaful;
- disbursement;
- developer / strata related payment(视项目而定);
- renovation;
- deposit;
- moving cost。
所以千万不要看到“100% Stamp Duty Exemption”就把预算只做到 down payment。
Benefit 2:Housing Loan Interest Tax Relief
这跟上面的 stamp duty 是另一回事。
HASiL 目前列出的 first residential property housing-loan interest tax relief:
如果 SPA 在:
1 January 2025 – 31 December 2027
签署,而且符合 qualifying conditions:
House price up to RM500,000
最高 relief:
RM7,000 per year
House price above RM500,000 up to RM750,000
最高:
RM5,000 per year
这篇集中讲 RM500k,所以我们的上限是 RM7,000。
这里最重要:RM7,000 不是政府直接给你 RM7,000
这点一定要分清楚。
Tax relief ≠ cash rebate。
它的作用是减少你的 chargeable / taxable income。
例如符合条件的人一年实际支付 qualifying housing-loan interest RM6,000:
那一年最多 claim 实际符合条件的 RM6,000,而不是自动拿 RM7,000 cash。
如果 qualifying interest RM10,000:
- relief 上限仍然是 RM7,000。
真正省下多少 income tax,要看你自己的 taxable income 和 marginal tax rate。
可以 Claim 几年?
HASiL Public Ruling 的例子说明,first-home housing-loan interest relief 可以从第一次实际支付 qualifying interest 的 Year of Assessment 开始,连续 3 个 YA claim。
例如:
- SPA 2027;
- 2028 才开始付 loan interest;
符合条件的话,可能从 YA 2028 开始计算连续三年。
不是永远每年都可以 claim RM7,000。
什么条件要特别确认?
HASiL 当前 guidance 的重点包括:
- first residential property;
- 买来作为自己的 place of residence;
- limited to one unit;
- SPA 必须在规定期间签署;
- house price 要在 qualifying band;
- claim 的是实际 qualifying housing loan interest。
签 SPA 前,尤其如果你过去已经有 property ownership、joint ownership 或特殊 property arrangement,最好先确认自己是否仍然符合“first residential property”的 tax definition。
Stamp Duty Exemption vs Tax Relief:不要再混了
| 项目 | Stamp Duty Exemption | Housing Loan Interest Tax Relief |
|---|---|---|
| 什么时候有作用 | 买房 transaction 时 | 报 income tax 时 |
| RM500k first home | 100% qualifying transfer + loan stamp duty exemption | Up to RM7,000 qualifying interest/year |
| 是不是 cash payout | 不是 | 不是 |
| 会不会直接减少 loan principal | 不会 | 不会 |
| 关键期限 | SPA 2026–2027 | SPA 2025–2027 + qualifying interest rules |
简单说:
Stamp duty exemption = 买房 transaction 少付一部分 tax。
Housing-loan interest relief = 报税时减少 taxable income。
那要怎么 Claim Housing Loan Interest Relief?
实际 filing 时,应在 individual income-tax relief section 申报符合条件的 first residential property housing loan interest。
你应该保留:
- SPA;
- loan agreement;
- bank annual loan / interest statement;
- proof of interest payment;
- 与 property ownership 相关的 supporting documents。
HASiL 也提醒 taxpayer 应保留 tax supporting records 一般长达 7 年,以备 review。
不要把整个月供全部当成 interest claim。
Housing-loan instalment 里面有:
- principal;
- interest。
这个 relief 针对的是符合条件的 interest paid。
第一次买房,不要只看月供
假设银行告诉你:
“Monthly instalment 负担得起。”
还没结束。
你还应该问自己:
- Down payment 后还剩多少 emergency fund?
- Lawyer / loan / valuation cost 有没有算?
- Renovation 有没有 budget?
- Maintenance fee / sinking fund 有没有?
- 每月水、电、internet、assessment / quit rent 等 recurring cost 有多少?
- 如果利率变化,monthly instalment 会不会变?
- 家里突然需要维修时有没有 cash buffer?
房子不是签 SPA 后只剩下 monthly loan。
RM500k First Home:最简单的结论
如果你符合 2026–2027 first-home stamp-duty exemption,而且用 RM450k loan:
Stamp duty example saving ≈ RM11,250
另外,如果符合 housing-loan interest tax relief:
每年最多 RM7,000 qualifying interest relief,最多连续 3 个 YA,视实际条件而定。
但这两项 benefit 都不代表你已经算完买房成本。
真正稳妥的做法是:
不要只看月供;签 SPA 前,把 stamp duty、legal、loan、装修和入住后的固定费用全部放进预算。
这期速递对你有用?转给需要的人。
大马政策与热点,每周 2–3 条,每条一句「所以呢」。