BERKAT Deepavali 2026: Who Can Apply for Up to RM30,000 in TEKUN Financing at 3%?
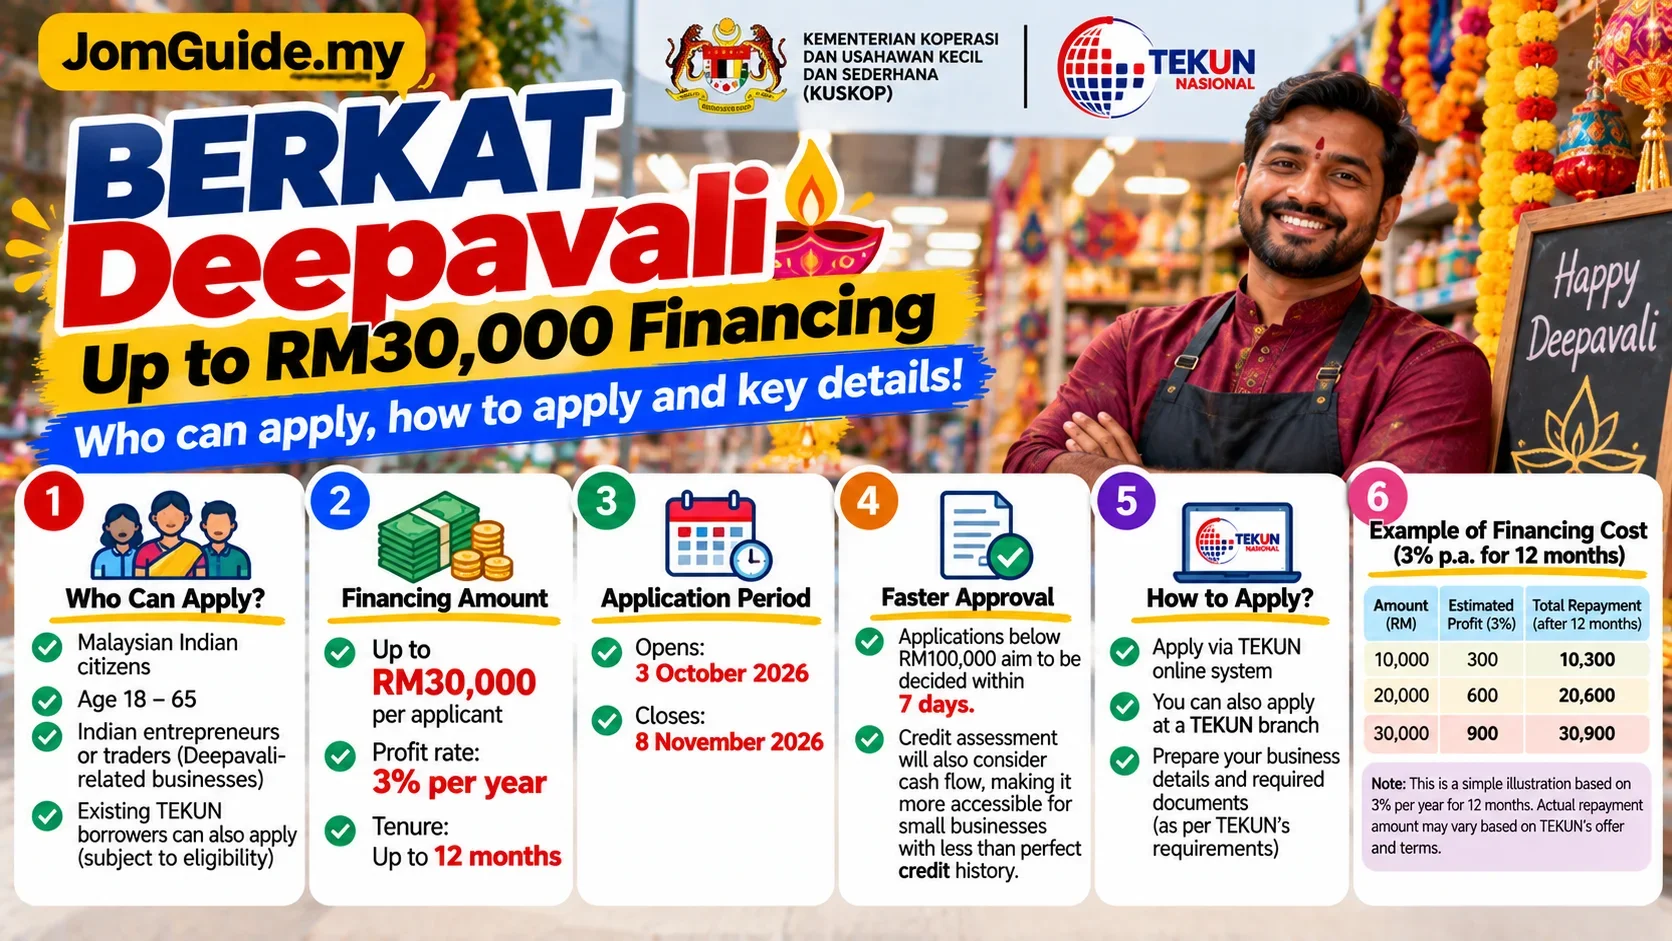
BERKAT Deepavali 2026 is open for eligible Malaysian Indian entrepreneurs and traders who need short-term working capital ahead of the festival. Financing is up to RM30,000 at 3% per annum for up to 12 months.

Source: Source: KUSKOP announcement reported by Bernama, 3 Oct 2026; TEKUN application channels
If you run a Deepavali-related small business and need short-term money to increase stock, BERKAT Deepavali is worth checking.
KUSKOP announced the scheme on 3 October 2026 through TEKUN Nasional, with:
- maximum financing: RM30,000
- profit rate: 3% per annum
- tenure: up to 12 months
- application period: 3 Oct – 8 Nov 2026
- total allocation: RM30 million
The scheme is intended mainly as short-term working capital for Indian entrepreneurs and traders preparing for Deepavali.
But the first rule is simple:
available financing does not mean you should automatically borrow.
Check eligibility, then check whether your business cash flow can support repayment.
Who can apply?
The announced core criteria include:
- Malaysian citizen;
- member of the Indian community;
- aged 18–65;
- entrepreneur or trader involved in Deepavali-related business;
- financing used as relevant working capital.
Existing TEKUN entrepreneurs may also apply, provided total financing received does not exceed:
RM100,000
Every application remains subject to assessment.
Meeting the basic profile does not guarantee approval.
What businesses is the scheme aimed at?
The announcement specifically highlights small traders and hawkers needing extra stock or festive preparation, including areas such as:
- food and beverage;
- clothing;
- Deepavali-related equipment;
- festive supplies;
- bazaar trading;
- Little India businesses.
If your business has no meaningful connection to Deepavali activity, do not assume the scheme automatically fits simply because the rate looks attractive.
How much can you borrow?
Up to:
RM30,000
That is a maximum, not an automatic approved amount.
The final amount can depend on:
- business need;
- cash flow;
- credit assessment;
- application information;
- TEKUN's evaluation.
Start with how much working capital the business genuinely needs, not with the maximum you are allowed to request.
What does 3% per annum roughly mean?
The official headline rate is:
3% per annum
For a very simple 12-month illustration, if 3% were applied to the full principal for a year:
| Financing | Simple 3% annual illustration |
|---|---|
| RM10,000 | RM300 |
| RM20,000 | RM600 |
| RM30,000 | RM900 |
This table is only to show the rough scale of a 3% annual rate.
The actual TEKUN repayment schedule, calculation method, monthly instalment and any applicable charges are governed by the official financing offer and agreement.
Do not use the table as a final quotation.
Why should you not focus only on the low rate?
Because the biggest risk for a small business is often not the headline rate.
It is cash flow.
You may borrow RM30,000 for festive stock, but what happens if:
- stock does not sell;
- sales come in below forecast;
- supplier payments fall due;
- rent and staff costs continue;
- demand drops after Deepavali?
Even low-cost financing becomes stressful if the business cannot turn stock back into cash quickly enough.
Ask:
How fast will this money turn back into cash?
What if your credit history is not strong?
KUSKOP said applicants with weaker credit records may also be assessed using factors such as:
- cash flow;
- alternative credit assessment methods.
That flexibility is useful.
But it does not mean poor credit guarantees approval.
Every application remains subject to proper auditing, governance and assessment.
A better interpretation is:
credit history may not be the only factor, but the application still needs to make financial sense.
Application deadline
The scheme is open from:
3 October to 8 November 2026
Applications can be made through:
- the TEKUN Online Application System;
- TEKUN Nasional branches nationwide.
Do not wait until 8 November to start checking requirements.
If documents or information are missing, a last-day application gives you little room to fix anything.
Does approval really take seven days?
KUSKOP said financing applications below RM100,000 are targeted for decisions within:
seven days
and agencies have been instructed to expedite BERKAT Deepavali processing.
Treat that as a processing target, not a guaranteed promise that cash will be in your account exactly seven days after applying.
Actual timing can still depend on:
- application completeness;
- assessment;
- supporting documents;
- approval;
- disbursement.
Practical application flow
1. Confirm the scheme fits you
Check:
- Malaysian Indian citizen;
- age 18–65;
- Deepavali-related business activity;
- genuine working-capital need.
2. Decide the amount you actually need
Do not automatically enter RM30,000.
Calculate:
- stock purchase;
- supplier deposits;
- bazaar or logistics cost;
- existing cash;
- expected sales;
- risk of unsold stock after the festival.
3. Prepare business and identity information
The exact document list should follow the live TEKUN application system.
As a practical preparation step, organise relevant:
- identification;
- business registration or permits where applicable;
- business information;
- bank or transaction records;
- cash-flow evidence;
- existing financing information.
Use the official checklist if it asks for additional documents.
4. Apply online or at a TEKUN branch
Use the official TEKUN application route.
Do not hand sensitive identity or banking documents to an unknown third-party “agent”.
5. Wait for assessment
The application will be assessed against the programme and business circumstances.
Cash flow and alternative factors may be considered where credit history is weaker.
6. Read the offer before accepting
If approved, check:
- approved amount;
- tenure;
- repayment schedule;
- profit calculation;
- charges;
- payment dates;
- late-payment or default terms.
Approval itself is not a reason to accept financing you do not need.
Should you take RM10k, RM20k or RM30k?
There is no universally “best” amount.
The right question is:
How much can the business productively use and safely repay?
If your real stock need is RM8,000–RM10,000, borrowing the full RM30,000 simply because it is available creates an unnecessary obligation.
Do a basic cash-flow stress test
Write down:
Money in
- current cash
- expected Deepavali sales
- normal monthly sales
Money out
- stock
- rent
- staff
- suppliers
- transport
- utilities
- existing financing
- new BERKAT repayment
Then ask:
If Deepavali sales are 30% lower than expected, can the business still repay?
If the answer is unclear, reconsider the amount before borrowing.
Bottom line
BERKAT Deepavali offers useful terms for the right business:
- up to RM30,000;
- 3% p.a.;
- up to 12 months;
- dedicated festive working capital;
- an expedited assessment target.
But the right applicant is not someone who borrows simply because the rate is low.
It is someone who knows:
- exactly where the money will go;
- how it supports sales;
- and how repayment will be covered.
Use this order:
check eligibility → calculate the real funding need → stress-test cash flow → apply.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.