BNPL Unexplained Charges in Malaysia: How to Complain to SKP
An unexpected SPayLater, Atome or other BNPL fee? Know your Malaysian consumer credit rights and how to complain to the provider and SKP.

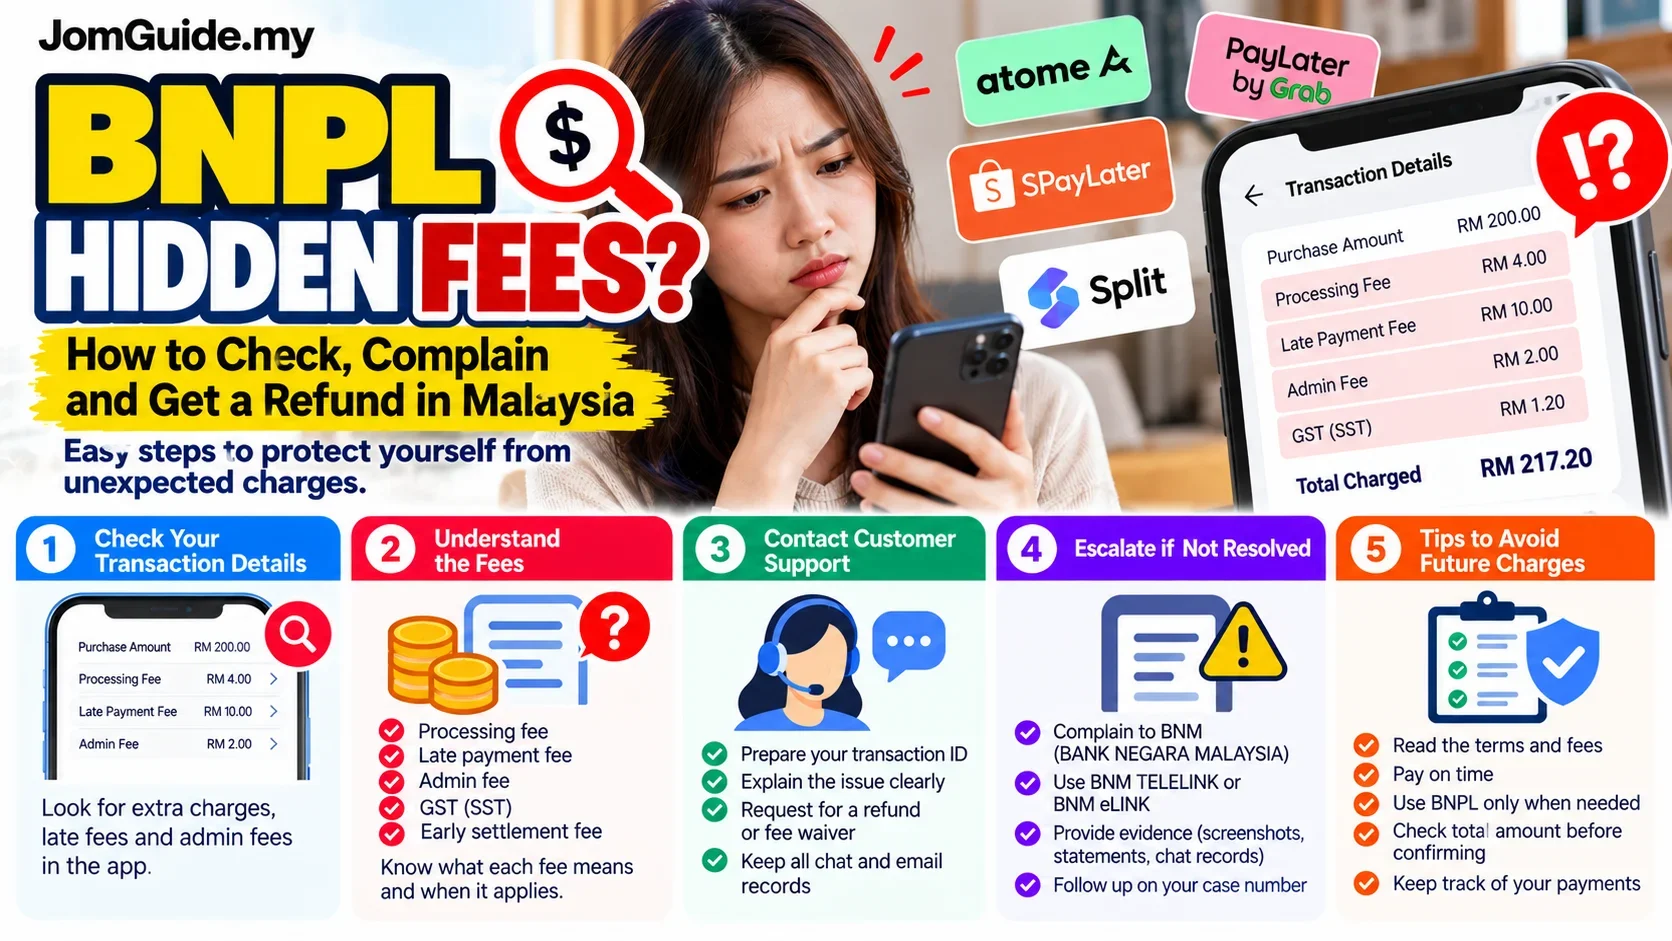
Source: Consumer Credit Commission (SKP); checked 25 October 2026
Updated 25 October 2026. An unexplained fee on a BNPL statement deserves an explanation, but it does not automatically prove wrongdoing. Whether you use SPayLater, Atome or another buy-now-pay-later service, the starting point is the same: identify the fee, check the agreement and preserve evidence.
Which charges should you question?
A provider may charge disclosed processing or late fees depending on the product. Problems may arise when a fee was not clearly disclosed, the statement includes duplicate charges, a timely payment is marked late, or a refund is missing. Compare the original checkout terms, the instalment schedule and your payment history. Ask the provider to identify the contract clause and calculation behind a charge.
Your rights under Malaysia's consumer credit rules
The Consumer Credit Commission (Suruhanjaya Kredit Pengguna, or SKP) says the Consumer Credit Act 2025, Act 873, promotes transparent fee disclosure, fair treatment and accessible complaint mechanisms. The regime took effect in stages in 2026. SKP's jurisdiction covers relevant non-bank credit providers; banking products and other businesses can fall under a different regulator. Check which legal company actually extended your credit.
Two hypothetical disputes
RM500 order with RM30 you cannot explain
Suppose a RM500 purchase appears with an extra RM30 on the BNPL statement. Review the pricing disclosure, due dates and payment records. Ask whether the RM30 was an agreed fee, an alleged late charge or an error. If you paid on time, attach proof and request an itemised explanation.
RM1,500 order cancelled but RM60 remains
A merchant confirms that your RM1,500 order was cancelled, yet the app still shows a disputed RM60. Keep the refund receipt and request an updated statement, transaction timeline and explanation of the charge.
RM30 and RM60 are invented examples for education, not actual fee schedules for any brand. Do not assume an amount is illegal without examining the terms.
How to complain: provider first, SKP second
Step 1: Collect a paper trail
Keep the order number, date, original instalment terms, screenshots, proof of payment, merchant refund notification and previous support messages. Do not publicly share sensitive identity numbers or banking credentials.
Step 2: File a formal complaint with the provider
Use the official app or website. State the disputed fee and date, explain why you believe it is wrong, and request a specific outcome such as an explanation, correction or justified refund. Ask for a case reference and written decision.
Step 3: Escalate through the correct regulator
SKP's complaint guidance says to approach the provider first. If you cannot contact it, receive no satisfactory response or disagree with its resolution, use SKP CARE where the provider falls under SKP's remit.
Submitting a complaint does not automatically cancel debt or guarantee reimbursement. If part of your balance is disputed, ask the provider in writing how to handle payments that are not disputed.
Frequently asked questions
Does 0% interest mean no other charges? Not necessarily. Read the entire fee disclosure, including late-payment and processing terms.
Can I complain about a repayment reminder? You can dispute inaccurate amounts or unfair handling while continuing to clarify any legitimate outstanding obligations.
Is SKP the complaint body for every BNPL product? No. The regulator depends on the underlying legal provider and product category.
Practical takeaway
Before accepting a plan, check the total repayable amount, not just the instalment size. After a dispute begins, a clear written record is more useful than arguing with screenshots alone.
For BNPL fundamentals and repayment risks, read JomGuide's earlier BNPL explainer.
Official references: SKP consumer FAQ, SKP BNPL guidance, SKP complaint channels.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.
Related articles
More in Jom Money-
Driving Into Singapore From 2027: VEP Rises to S$50 a Day, Free Days and Evening Hours Scrapped. Here's What It Costs You
-
STR 2026 Phase 4 Is Being Paid: Up to RM500 for Households, RM150 for Seniors, 4–6 November, New Recipients From the 16th
-
When Is STR 2026 Phase 4 Paid? Not Announced Yet: What You Can Do Now, Plus STR 2027 Applications