EPF i-Saraan, i-Suri and i-Saraan Plus: Who Can Get RM300, RM500 or RM600?
Self-employed in Malaysia? Compare EPF's 2026 i-Saraan, i-Suri and driver-only i-Saraan Plus incentives, annual contribution targets, eligibility and sign-up steps.

Source: KWSP official i-Saraan, i-Suri and i-Saraan Plus programme pages
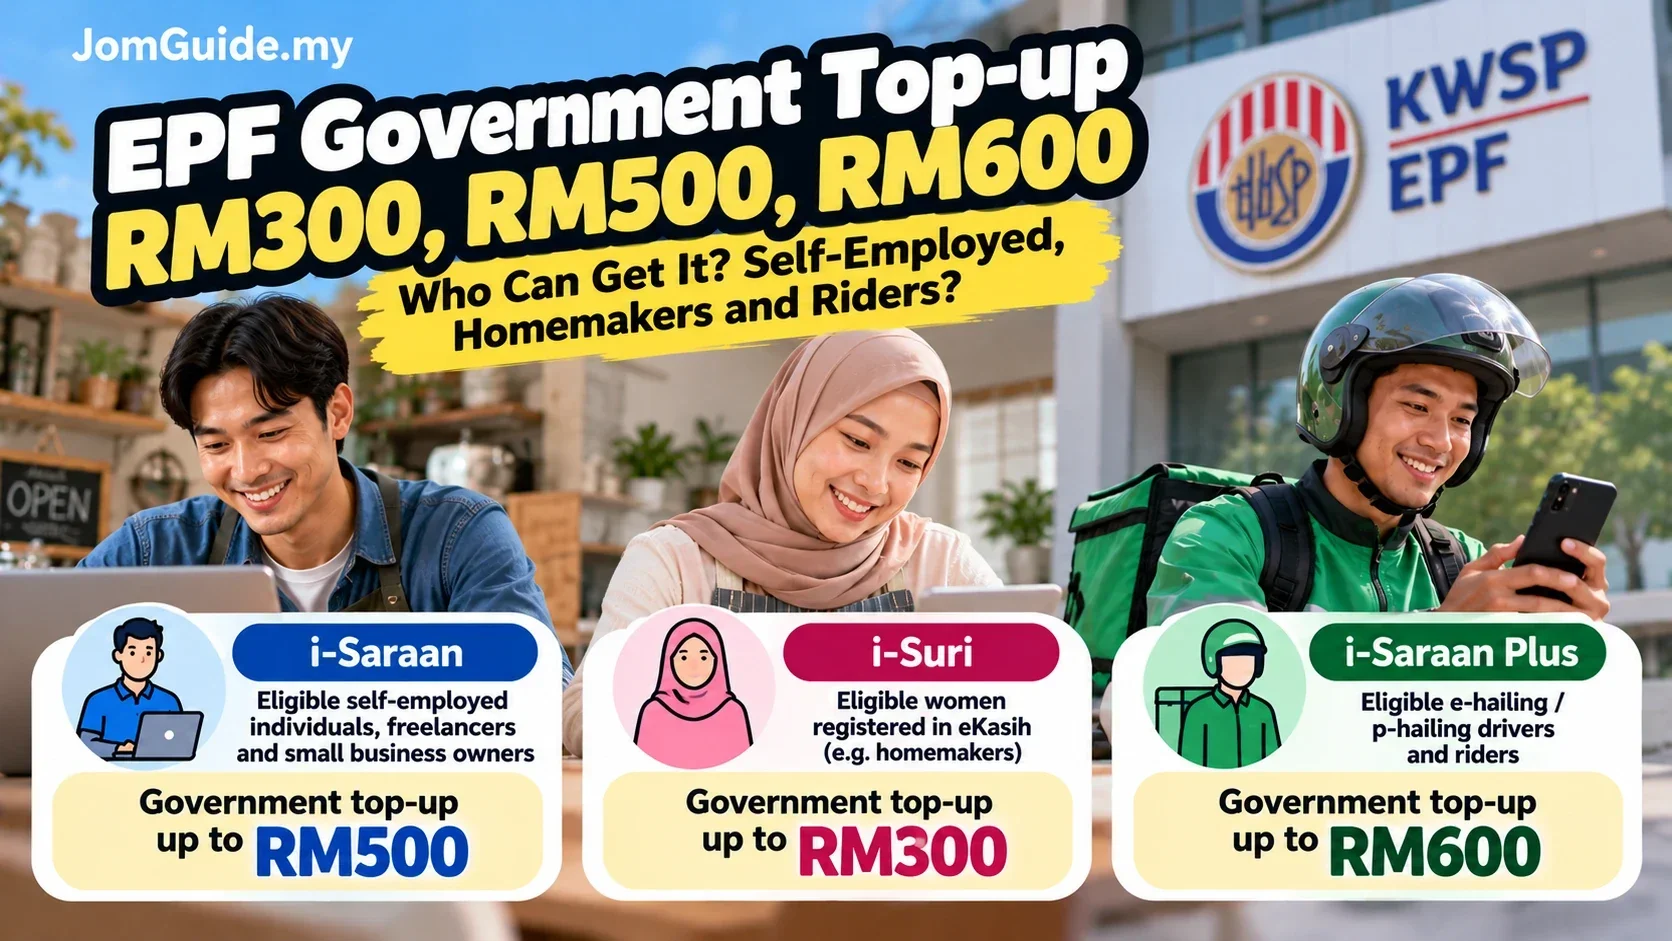
If you earn money from your own work but have no employer making regular EPF contributions, check i-Saraan first. In 2026, EPF also has targeted incentives for eligible women in eKasih and e-hailing or p-hailing drivers. The figures RM300, RM500 and RM600 are maximum government matching incentives, not cash handed to everyone.
Which programme fits your situation?
| Programme | Intended group | Matching incentive in 2026 | Contribution needed to reach annual cap |
|---|---|---|---|
| i-Saraan | Eligible self-employed workers, freelancers and people with no fixed income | 20%, up to RM500/year | RM2,500/year |
| i-Suri | Eligible women registered in eKasih | 50%, up to RM300/year | RM600/year |
| i-Saraan Plus | Eligible self-employed e-hailing or p-hailing drivers using participating platform contribution channels | 20%, up to RM600/year | RM3,000/year |
Those contributions are your own savings deposited into EPF. The matching incentive is added into EPF subject to eligibility and caps. It is not an instant cash reward or guaranteed amount without contribution.
Self-employed: why i-Saraan may matter most
Examples include freelance designers, small stall operators, own-account delivery workers and self-employed service providers. Eligibility is based on KWSP's rules, not simply on having an SSM registration. KWSP describes i-Saraan for eligible Malaysian EPF members under age 60 who are self-employed or have no fixed income; its FAQ also covers certain workers under pension schemes.
The current matching formula is 20% of eligible voluntary contributions, up to RM500 per year.
- Put in RM500 during the year: illustrative matching incentive RM100.
- Put in RM1,000: RM200.
- Put in RM2,500: reach the RM500 annual cap, if otherwise eligible.
- Put in RM4,000: the incentive still caps at RM500 for that year.
The lifetime i-Saraan incentive cap is RM5,000, or until age 60, whichever arrives earlier. EPF pays incentives subject to the government's funding and its credited-payment schedule; do not assume an instant RM500 appears after your deposit.
Rider or e-hailing driver: Plus is different
i-Saraan Plus begins with i-Saraan registration but is intended specifically for eligible e-hailing and p-hailing drivers. You must make a qualifying voluntary contribution through an eligible platform provider to join the Plus arrangement. Existing i-Saraan members do not need a second registration; platform-based qualifying contribution triggers participation.
Once participating, EPF also allows contributions via existing channels to help reach the yearly RM3,000 saving target. Matching is 20%, capped at RM600 annually and RM6,000 over a lifetime, subject to age and programme terms.
A rider is not automatically entitled to both i-Saraan RM500 and Plus RM600 in one year. EPF explicitly says only one of those incentives can be paid in a given year, and its Plus FAQ includes a rule that members must not be receiving mandatory employer contributions for the relevant eligibility.
If you do platform work as a side gig while salaried elsewhere, check the employer-contribution condition with KWSP before assuming Plus applies.
i-Suri is not for every housewife
i-Suri is intended for eligible Malaysian women registered in the eKasih National Poverty Data Bank, with their status checked against the relevant cutoff (the official current page refers to 30 November of the previous year). Being a homemaker alone is not sufficient.
Eligible members below 60 receive 50% matching up to RM300 per year by contributing RM600. The lifetime incentive cap is RM3,000, or age 60, whichever comes first. If unsure about eKasih status, verify it before contributing specifically in expectation of i-Suri benefits.
How much should I save each month?
The programme calculates incentives from eligible contributions received within the year, not from a mandatory equal monthly payment. If spreading the annual target over 12 months, the averages are:
| Programme | Annual contribution target | Monthly average over 12 months |
|---|---|---|
| i-Suri | RM600 | RM50 |
| i-Saraan | RM2,500 | about RM208.34 |
| i-Saraan Plus | RM3,000 | RM250 |
Starting in October? The 12-month figures are not enough to reach this year's maximum if you have contributed nothing so far. For example, over the final three months of a calendar year, RM2,500 would average roughly RM833.34 a month; first check your year-to-date eligible contributions and whether payments can be processed in time. Do not empty an emergency fund purely to chase the incentive cap.
How to register and contribute
i-Saraan
- Confirm you are an EPF member and check eligibility on the official KWSP i-Saraan page.
- Register through KWSP i-Akaun, eligible online registration, an EPF self-service terminal or an EPF branch.
- Contribute through the approved channels and check that amounts are recognised as i-Saraan contributions.
- Verify the total for the current calendar year in your EPF record.
i-Suri
Check your eKasih eligibility first; register through i-Akaun's i-Saraan/i-Suri route or KWSP's other prescribed channels. KWSP explains the data match used for i-Suri classification.
i-Saraan Plus
Register under i-Saraan, arrange platform-provider voluntary contributions for your e-hailing/p-hailing work, then verify they were received and tagged correctly. Don't assume a general voluntary payment alone starts Plus.
What happens to the money?
Contributions become EPF retirement savings, with account allocations and withdrawal restrictions governed by EPF rules. Under the current i-Saraan page, the matching government incentive for members below 55 goes to Akaun Persaraan, so it should not be marketed as spendable cash. Contributions are generally final, and the full contribution amount is not freely refundable because your circumstances change.
The straightforward decision: self-employed → check i-Saraan; eligible eKasih woman → check i-Suri; platform rider/driver → check i-Saraan Plus. Verify all conditions before deciding how much you can afford to save.
Official sources: KWSP i-Saraan, i-Suri, i-Saraan Plus.
Useful? Forward it to someone who needs it.
Malaysian policy and hot topics, 2–3 items a week, each with a one-line “so what”.